Insurance digital marketing should bring in people who finish a quote and buy a policy, within IRDAI rules in India and FCA rules in the UK. It suits providers and brokers who sell or generate applications through their own website. You get plain-language cover and comparison pages, a shorter quote journey, compliant campaigns and a monthly report on bound policies and renewals.
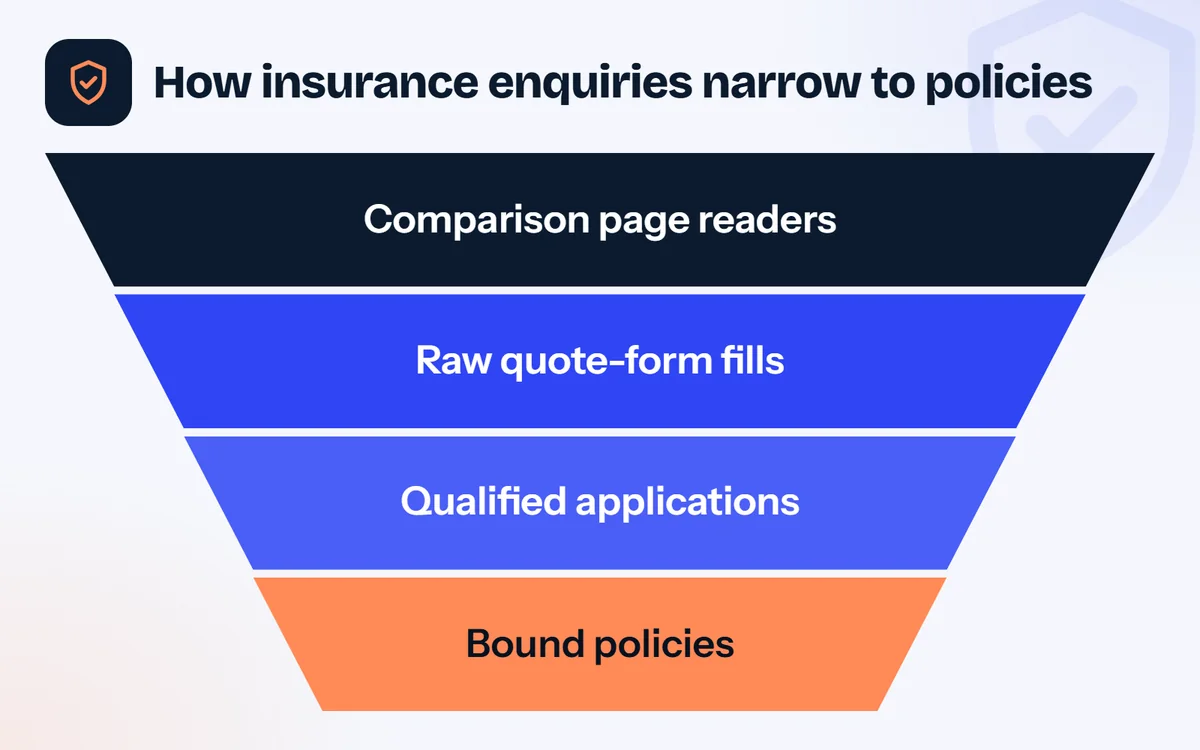
Why insurance quotes stall before a policy is bound
Your dashboard shows quote starts climbing, yet only a small share become bound policies. The marketing report looks busy while cost per policy keeps rising.
The causes usually sit in the funnel rather than the media plan. Product pages list benefits but bury exclusions and excess. Quote forms ask every question up front without saying why. Campaigns are judged on form fills, and aggregators take the generic price searches you were paying to compete for.
In the UK the economics also changed. Since the FCA banned price walking from 1 January 2022, renewing home and motor customers cannot be charged more than a new customer for the same cover. An expensive acquisition can no longer be recovered quietly at renewal, so acquisition has to be efficient and retention has to be earned through service and fair value.
Which insurers and brokers this suits, and which it does not
This approach suits insurers, brokers and intermediaries whose own website plays a real part in the sale: motor, home, health, life, travel, business or specialist cover. It is strongest for specialist products, where buyers search for a particular type of cover and aggregators have less to offer them.
It is not a good fit if every sale goes through aggregators or a tied agency force, or if you want campaigns live before compliance has agreed how each product may be described. We will also be straight with you: insurance is not a sector where we have past client work. The closest is our work with banks and fintech businesses, covered on our finance and banking digital marketing page.
What insurance digital marketing includes
- Cover pages in plain language that set out what is covered, what is excluded and the excess, with the required disclosures built in
- Comparison content that is honest about who each policy suits and who it does not, kept accurate and fairly presented
- SEO for specialist products, brand searches and questions about cover, where aggregators do not win every result
- Paid search and social campaigns aimed at people ready to quote, with every claim agreed before launch
- A shorter quote journey that explains each question, saves progress and lets people come back later
- Claims stories and verified service reviews, because the claims experience is what policyholders remember
- Renewal emails that explain any change early and clearly
- Tracking that separates quote starts, completed quotes and bound policies, with applications scored before they reach your sales team
Quote-journey changes follow our conversion rate optimisation method, and application scoring follows our lead generation services.
Getting compliance sign-off without the bottleneck
In India, IRDAI rules govern insurance advertisements and require benefits and conditions to be represented accurately. In the UK, financial promotions must be fair, clear and not misleading, including on social media, and the FCA's guidance FG24/1 warns that unauthorised influencers promoting regulated products may commit an offence.
Your compliance team keeps final sign-off. We make approval quicker by drafting to the rules from the start, checking each claim against the policy wording and sending changes in planned batches instead of a steady trickle.
How we would run your insurance account, from audit to monthly report
It begins with a free audit of your site, quote journey, rankings and competitors, delivered in 3 to 5 business days. From that audit comes a 90-day plan with priorities and a fixed monthly price.
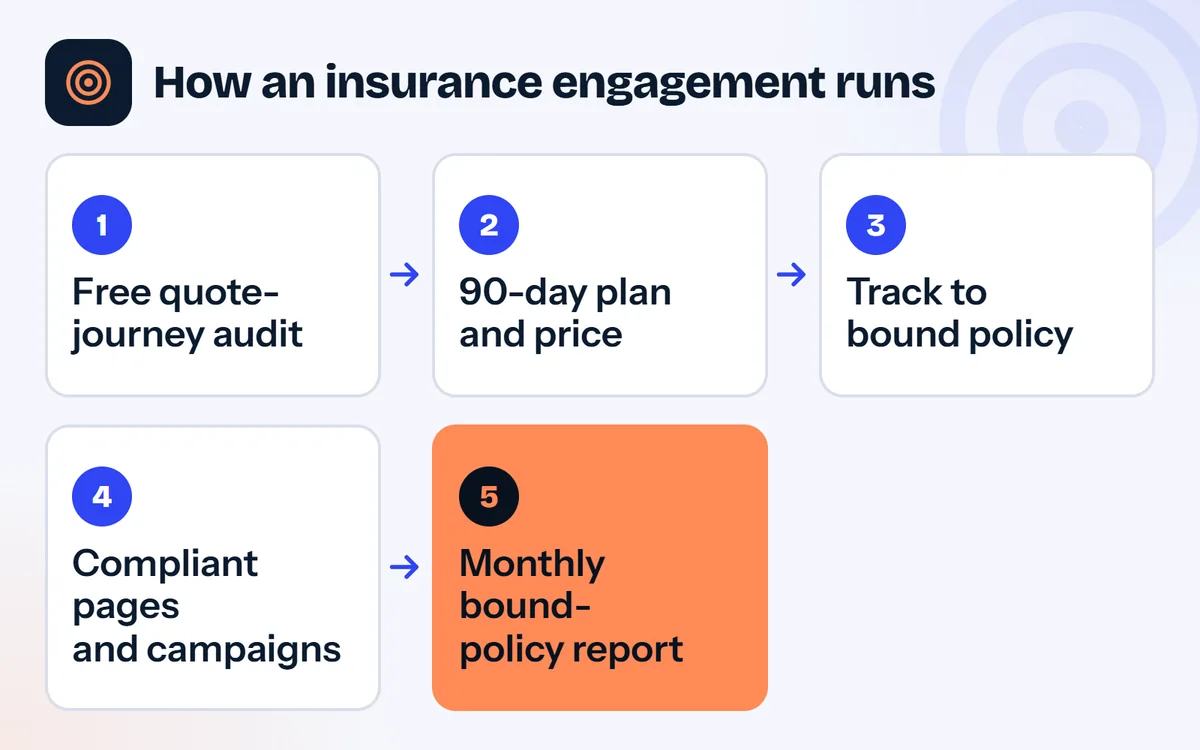
The first job in that plan is tracking. If your data cannot follow a visitor from first click to bound policy, every later decision is a guess, so we connect the quote system and analytics before changing campaigns.
Next come the cover pages, the quote journey and the campaigns for your most profitable products, run end to end by a named senior specialist. Each month you get one plain report on completed quotes, bound policies, cost per bound policy and renewal rate, with rankings and traffic as context.
What we would check first in an insurance funnel
We have no published insurance case study, and we will not borrow a result from another sector to suggest otherwise. Our published case studies come from EdTech and ecommerce brands in India.
What we would look at first is the gap between completed quotes and bound policies, the exact question where people abandon the quote form, and the cover pages that attract visits but no applications. Together those show whether the problem is the audience, the page or the journey.
Working with us on insurance marketing from India or abroad
Insurers and brokers in India can reach the team on WhatsApp at +91 70096 23687, review drafts on calls in IST and visit our office in Mansa, Punjab. Copy is written to IRDAI rules before it reaches your compliance team.
For firms in the UK and elsewhere, we agree a working slot inside your business hours for reviews and approvals. The contract rolls monthly, your ad, analytics and website accounts stay in your name, and promotions are prepared to FCA rules.